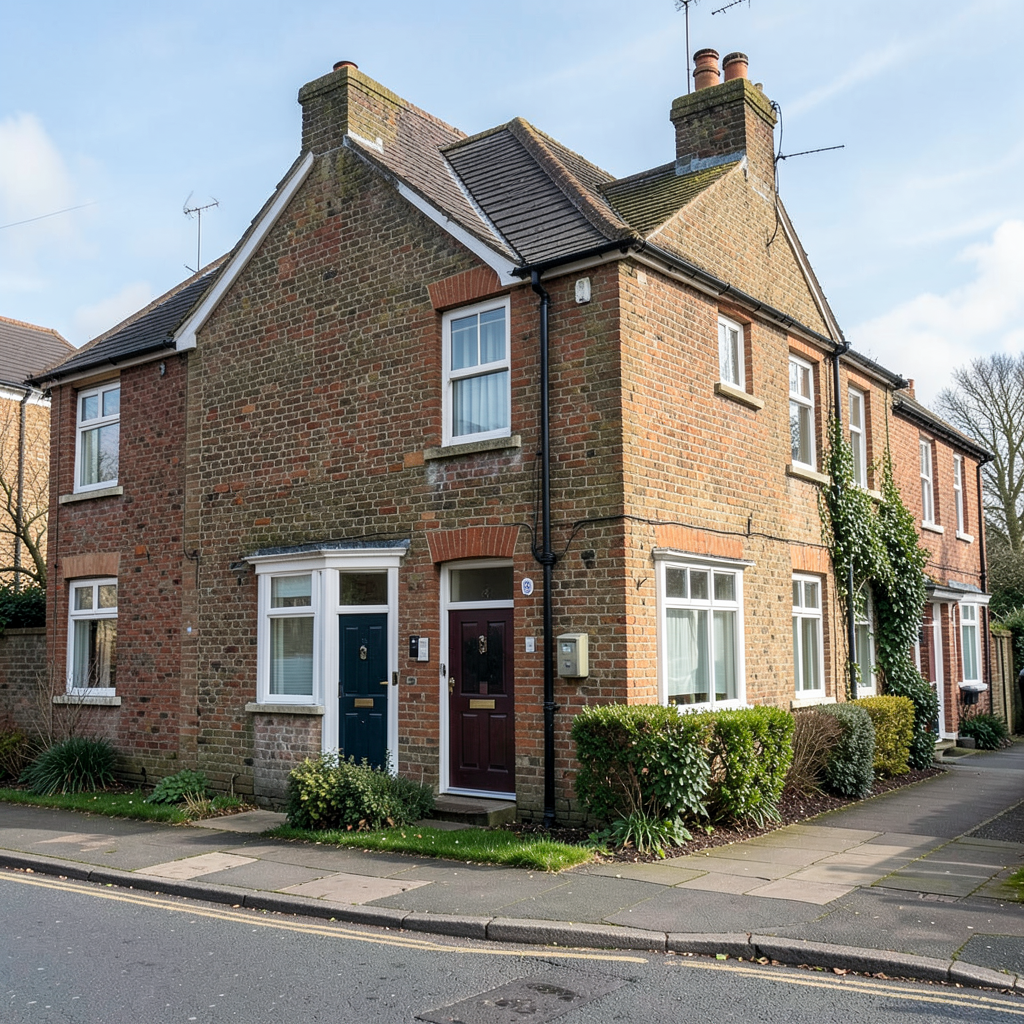
A member of Generation Z working in property sales has challenged the prevailing assumption that homeownership lies beyond reach for young adults, citing data that paints a more nuanced picture than many social media posts suggest.
Estate agent Josh Endacott, who represents 1st Avenue, argues that although soaring property prices dominate online discourse, the underlying figures reveal more hopeful possibilities for prospective buyers willing to explore their options thoroughly.
The discussion carries particular weight in the capital, where housing costs present the starkest challenges nationally.
Statistics from the Office for National Statistics indicate that during 2025, a typical London property commanded a price equivalent to 10.6 times average earnings, substantially higher than the 7.6 ratio recorded across England as a whole.
Within the borough of Kensington and Chelsea, which ranks as the least affordable local authority in England and Wales, residential properties fetch 25.2 times typical wages.
Those renting privately in the capital also contend with substantial financial pressures.
Data shows that in 2024, London tenants allocating private rental accommodation devoted 41.6 per cent of median household income to housing costs, comfortably exceeding the recognised 30 per cent threshold beyond which spending becomes generally considered unaffordable.
Endacott contends that the London market illustrates precisely why purchasers should carefully evaluate deposit requirements, potential family contributions, geographic alternatives, and applicable support programmes before dismissing homeownership as unattainable.
Assistance from relatives can substantially improve prospects for those entering the property market.
Research from UK Finance demonstrates that during 2024, London first-time buyers proceeding without parental or familial financial backing typically required deposits approaching £150,000, whereas those receiving such support needed sums closer to £225,000.
The agent emphasises that misconceptions about deposit thresholds represent one of the most common obstacles he encounters.
While the national average deposit figure appears daunting, this calculation receives considerable distortion from London and the southeastern region.
Across extensive areas of the Midlands and northern England, properties marketed to first-time purchasers remain comfortably below the £200,000 mark, and several major mortgage providers now offer products requiring initial outlays starting from £5,000.
Endacott advises younger buyers to consider expanding their geographic horizons rather than limiting themselves to familiar areas.
The assumption that purchasing must occur in the locality where one grew up or currently rents often proves unnecessarily restrictive.
The normalisation of remote and hybrid employment arrangements has fundamentally altered the financial calculus for numerous young workers, enabling individuals to command metropolitan salaries while securing properties in towns where their financial resources stretch considerably further.
Government initiatives designed to assist younger buyers frequently suffer from misunderstanding, according to Endacott.
The First Homes programme, which enables qualifying purchasers to acquire designated new-build properties at discounts ranging from 30 to 50 per cent below market rates, and the Mortgage Guarantee Scheme, which underwrites mortgages with loan-to-value ratios between 91 and 95 per cent, represent what he describes as relatively accessible financial planning tools.
However, Endacott maintains transparency regarding genuine difficulties facing buyers in the capital and southeastern corridor, particularly those without access to family wealth.
Data indicates that more than half of all first-time buyers continue to depend upon some form of familial financial contribution, a resource unavailable to certain individuals.
He acknowledges this disparity warrants acknowledgment rather than dismissal.
Nevertheless, he argues that recognising these obstacles should not lead young people to abandon property purchase ambitions entirely.
Understanding which support mechanisms exist and deploying them strategically offers a more productive approach than surrendering to fatalism.
Endacott expresses concern that pervasive negative messaging risks becoming self-fulfilling.
Should young adults internalise the belief that property ownership remains permanently beyond their grasp before conducting proper research, they may neglect to accumulate savings, investigate applicable schemes, or examine locations where realistic pathways onto the housing ladder exist.